
UNITING FAMILIES WITH THEIR GOALS
UNITING FAMILIES WITH THEIR GOALS
What is Home Loan?
A home loan finances a property; mortgage insurance is a separate product.
A home loan or mortgage is money borrowed to buy or refinance a property, usually secured against it. Compare the interest rate, term, amortization, payments, fees, prepayment privileges and penalties. Mortgage insurance is a separate topic: creditor life insurance, personal life insurance and mortgage default insurance serve different purposes. The sections below explain these distinctions for discussion with third-party professionals.
Insurance associated with home loans
In Canada, various names are used for mortgage insurance and related products. Here’s a guide to distinguishing between each type of mortgage insurance.
Mortgage insurance
Mortgage protection
Mortgage default insurance
- Mortgage insurance, offered by your mortgage lender, safeguards your decreasing mortgage debt in the event of your passing. It is integrated into your monthly payments
- Also referred to as: mortgage life insurance, lender-provided mortgage insurance.
- This form of protection utilizes term life insurance tailored to align with your mortgage's amortization period. It offers a flexible and cost-effective protection product, granting your beneficiaries greater control over the utilization of the benefit.
- Also known as: mortgage protection through term life insurance, mortgage protection insurance, private mortgage insurance, mortgage protection life insurance.
- A (sometimes) mandatory, one-time insurance fee paid by Canadian homeowners if their initial down payment is below 20% of the total value of their mortgage home.
- Also known as: mortgage loan insurance, CMHC insurance.
How does Home Loan life
insurance work?
Personal term life insurance can provide a death benefit to the beneficiary you choose, subject to the contract. That benefit can help with a mortgage and other needs. Creditor mortgage life insurance generally pays the lender toward the insured debt. Underwriting, exclusions, benefit amounts and renewal rules differ. Neither type guarantees that every claim will be paid; compare the actual policy wording and suitability with an authorized third-party professional.
Creditor mortgage insurance versus personal life insurance
Compare the purpose, beneficiary, cost and conditions of each type of coverage.
Home Loan
- Only covers the decreasing, outstanding mortgage balance
- Only covers the borrower
- No flexibility to change amount or term
- Coverage reduces with monthly mortgage payments
- Coverage not guaranteed, only evaluated at claim
- Your lender is the beneficiary
- Generic rates, usually higher, and stay the same even with reducing coverage
- Coverage may be lost when switching lenders
- Can only be used by lender to pay the outstanding balance of the mortgage
Home Loan Life Insurance:
- Can cover everything from debts to family expenses and obligations like a conventional loan or property taxes
- Can cover you and your family
- Can increase coverage amount and term
- Consistent coverage throughout the term
- You choose a beneficiary under the policy rules.
- Premiums and acceptance depend on underwriting and product terms.
- Coverage can remain separate from your mortgage lender.
- Claims remain subject to the policy, exclusions and assessment.
Apply for a loan
Is Home Loan necessary for me?
Creditor life insurance is different from mortgage default insurance. The latter protects the lender and may be required for certain mortgages; creditor life coverage is a separate decision. Ask the lender which insurance is required, which is optional, what it costs and who receives the benefit.
Questions about loans?
Call +1 438 701 3770 to speak to third-party advisors right away, or book some time with them.
How long do you pay mortgage insurance for?
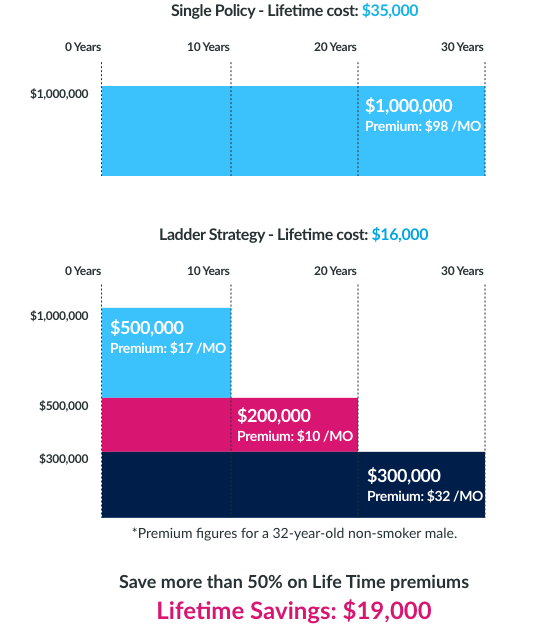
Is Home Loan worth it?
Assess value using a personalized comparison
Value depends on the coverage, premium, exclusions, existing protection and your circumstances. Compare creditor coverage and personal insurance using current written quotes. An authorized third-party professional can assess suitability; one type is not automatically the best choice for everyone.
Is mortgage insurance a misuse of funds?
Mortgage insurance is not considered wasteful expenditure in certain situations. If you are ineligible for private mortgage insurance through a term life policy or other insurance products that could cover your mortgage, mortgage insurance might be a viable option.
In rare instances where disqualification occurs due to family medical history or illness preventing approval for coverage, mortgage insurance becomes a worthwhile choice. Having mortgage insurance coverage is preferable to having no coverage at all.
Apply for a loan
What is the cost of Home Loan?
Mortgage borrowing costs depend on the amount, rate, term, amortization and fees. Insurance premiums are separate and depend on the coverage, age, health and other underwriting factors. Obtain current written mortgage and insurance quotes from the relevant third-party professionals. Unity can arrange an enquiry but does not operate an instant quote engine.
What is the average cost of Home Loan?
The price of a mortgage protection insurance policy (term life insurance) varies based on personal factors and the extent of coverage you seek. Age, smoking status, and health significantly influence the cost of a term life policy. The duration and amount of coverage required are typically determined by your remaining mortgage balance and the number of years of payments remaining.
Historical or illustrative examples retained from the original page. These are not current rates, limits or offers. Confirm the applicable terms with the provider.
| AGE | MALE | FEMALE |
|---|---|---|
| 25 | $31 | $22 |
| 35 | $33 | $26 |
| 45 | $75 | $54 |
| 55 | $223 | $155 |
| 65 | $716 | $487 |
Frequently asked questions
Term life insurance products come without any hidden catches or “gotcha” moments. They represent a transparent and affordable form of insurance, allowing you to maximize the financial protection you can acquire while staying within your budget.
Virtually all life insurance companies provide renewal options as a key feature of term life insurance policies. For instance, if you have a 10-year term life policy, it automatically renews for another 10 years at the end of the term, unless you decide to cancel your coverage. However, this renewal comes with an increased premium, and many Canadians may still qualify for a lower premium by applying for entirely new coverage.
Typically, companies permit policy renewal up to a specified age, like 70 or 75 years old. Once you reach that age, the policy becomes ineligible for renewal, and the coverage expires.
Unity can refer your enquiry to a third-party professional. Ask that professional which providers they represent and compare coverage, exclusions, premiums and service. The appropriate choice depends on your circumstances; Unity does not provide the suitability assessment or sell the policy.
Canada’s leading insurance companies offer distinct policies tailored to meet the unique coverage requirements of each Canadian. The key is having the freedom and knowledge to select the policy and provider that aligns with your specific situation.
That’s precisely why Unityfs collaborates with over 20 of Canada’s top insurance companies—the highest number among online brokers. We ensure you have an extensive array of options when choosing the insurance company to safeguard yourself and your loved ones. We can assist you in securing a life insurance plan from renowned providers such as Assumption Life, BMO Insurance, Canada Life, Canada Protection Plan, Desjardins, La Capitale, Empire Life, Equitable Life, Foresters, Humania, iA Group, ivari, Manulife, RBC, Sun Life, SSQ, and Wawanesa.
As noted earlier, the primary factors influencing the premiums set by all life insurance providers are age and health. Taking these criteria into account, it is highly beneficial to apply for life insurance coverage at an earlier age. Applying while younger is advantageous because it is less likely that any health conditions have impacted you, thereby minimizing the potential increase in the cost of your premiums.
Unlike permanent life insurance, term life insurance does not accumulate cash value or surrender value. This distinction is a key factor contributing to the affordability of term life insurance compared to permanent life insurance options, making it a more cost-effective means of financial protection.
No, there is no cashback at the conclusion of a term life insurance policy. Once the term expires, your coverage concludes, and premium payments are no longer obligatory. Term life insurance can be likened to leasing insurance for a specific, temporary requirement, rather than incurring additional costs to own the policy permanently.
Discuss the coverage amount and term with an authorized third-party professional. Consider debts, dependants, income replacement, existing assets, other insurance and affordability. Unity can arrange a referral; the professional provides the product comparison and advice.
Life insurance is essential for anyone with dependents or loved ones. However, due to their unique circumstances, single parents often shoulder a greater responsibility in the upbringing and protection of their children, and this extends to the crucial aspects of life insurance and financial protection.
Certainly, you can purchase insurance for your loved ones, but it requires their consent and knowledge that their life is being insured. The only exception would be in the case of children below the age of consent, where you are their legal guardian. In essence, we need to communicate with anyone you intend to insure, including your loved ones.
While health problems may not automatically disqualify someone from obtaining life insurance, they can significantly impact the cost of premiums. The price is likely to be influenced by the nature of the ailment, its diagnosis timeline, and its current impact on health. Our seasoned advisors can assist in assessing coverage options and connecting you with a life insurance company offering policies tailored to your specific situation. We provide support in applying for simplified non-medical insurance policies or guaranteed non-medical insurance coverage, whenever these options are the most suitable for our clients. Rest assured, our expert advice is readily available whenever you need it.
The duration of your term life insurance policy should align with your specific life insurance requirements.
A 30-year term life insurance policy is suitable for covering a new mortgage. Opting for a 20-year term life insurance policy can offer financial security for a new family. Meanwhile, a 10-year term life insurance policy may be utilized by seniors to handle final expenses or replace income for their beneficiaries. Online term life insurance provides flexibility, allowing you to choose the policy length that best fits your needs, whether it’s a 25-year term, 40-year term, or any duration in between.
Unityfs stands out as the digital brokerage representing the highest number of insurance carriers, guaranteeing that you discover the most competitively priced term life policy for your specific needs and budget. You have the convenience of comparing rates from 25 of the country’s top life insurance companies.
Easily compare term life insurance rates and apply for the coverage you require within minutes by clicking here!
Questions about loans?
Call +1 438 701 3770 to speak to third-party advisors right away, or book some time with them.